Introduction
Importing a car to Trinidad and Tobago in 2026 means three taxes on top of CIF: customs duty of 20% to 67.5% by fuel and engine size (10% for goods vehicles), a per-cc Motor Vehicle Tax, and 12.5% VAT. Qualifying small hybrids, and EVs up to TTD 400,000 CIF, pay none of them. Cars must be right-hand drive.
Trinidad and Tobago is a twin-island republic in the southern Caribbean, sitting just 11 kilometres off the coast of Venezuela. With a population of approximately 1.4 million people and one of the highest GDP-per-capita figures in the Caribbean basin, the country has a mature and active automotive market. Unlike many Caribbean neighbours that rely almost entirely on used vehicle imports from Japan, Trinidad and Tobago has historically maintained a strong new car dealership network — with authorized distributors for Toyota, Nissan, Hyundai, Kia, Mitsubishi, Ford, and several other global brands.
However, the range of models available through local dealers is limited. Buyers seeking vehicles not offered domestically — speciality hybrids and electric vehicles, larger SUVs, or performance cars — must import directly. The country drives on the left side of the road, so right-hand drive (RHD) is required: a left-hand-drive (LHD) vehicle cannot be registered unless it has been converted to RHD. That gives RHD imports from Japan, the UK, and India a natural advantage.
Trinidad and Tobago's import tax regime is built on three sequential taxes: a Customs Duty set by the CARICOM Common External Tariff line for the vehicle's fuel type and engine size, a Motor Vehicle Tax (MVT) charged per cubic centimetre of engine capacity, and a 12.5% Value Added Tax. On top of that sits a relief layer: a qualifying private hybrid or a lower-priced private EV is relieved of all three taxes. Recent changes — the TTD 400,000 cap on EV relief from 1 January 2026, the exclusion of mild hybrids in July 2026, the higher used-car age limit and the end of returning-national concessions — make this guide essential reading for anyone planning an import in 2026.
Quick Facts
| Detail | Information |
|---|---|
| Lead Agency | Customs and Excise Division, Ministry of Finance |
| Licensing Authority | Trade Licence Unit (TLU), Ministry of Trade and Industry |
| Registration Body | Licensing Authority of Trinidad and Tobago |
| Vehicle Inspection | Vehicle Maintenance Corporation of TT (VMCOTT) |
| Steering | Right-Hand Drive (RHD) required; LHD not registrable unless converted to RHD |
| Customs Duty | Petrol cars 20-67.5%, diesel cars 35-67.5%, non-qualifying hybrids 67.5%, EVs 20%, goods vehicles 10% (of CIF) |
| Motor Vehicle Tax (MVT) | TTD 5.00-75.00 per cc for private cars; TTD 2.50 per cc for goods vehicles; 25% lower for foreign-used vehicles |
| VAT | 12.5% on (CIF + Duty + MVT) |
| Hybrid Relief | 0% duty, 0 MVT, 0% VAT for private full hybrids up to 1,599 cc with an electric motor up to 105 kW (used: up to 3 years old) |
| EV Relief | 0% duty, 0 MVT, 0% VAT up to TTD 400,000 CIF; above that, 18% duty + per-kW MVT + 12.5% VAT |
| Used Car Age Limit | 6 years and under (private cars); 10 years and under (light commercial) |
| New Vehicle Imports | Permitted for any individual or company |
| Primary Seaport | Port of Spain (TTPOS) |
| International Airport | Piarco International Airport (POS) |
| Customs Clearance | 3-7 business days after duty payment |
| Currency | Trinidad and Tobago Dollar (TTD); ~6.8 TTD = 1 USD |
| Total Tax Burden (typical) | About 40% (small petrol car) to over 200% (large V8); 0% for qualifying hybrids and EVs |
Types of Cars That Can Be Imported
Trinidad and Tobago permits the importation of both new and used vehicles, but the rules differ significantly depending on the vehicle's age, condition, steering configuration, and powertrain.
New Vehicles
Any individual or registered company in Trinidad and Tobago can import a brand-new, right-hand-drive vehicle without an Import Licence. New vehicles are subject to the standard three-layer tax structure — Customs Duty, Motor Vehicle Tax, and VAT — unless they qualify for the hybrid or EV relief, and face no age-related restrictions or special licensing requirements. This makes new vehicle importation the most straightforward path for buyers seeking models not available through local dealerships.
Used Vehicles
Used right-hand-drive vehicles may be imported, but require an Import Licence issued by the Trade Licence Unit (TLU) of the Ministry of Trade and Industry. This licence must be obtained before the vehicle is shipped — failure to secure it in advance can result in the vehicle being denied entry or impounded at port.
Age restrictions for used vehicles (from 1 January 2026):
- Private cars (sedans, SUVs, station wagons) with gasoline, diesel, or CNG engines: 6 years and under from the date of manufacture
- Light commercial vehicles (pickups, panel vans): 10 years and under from the date of manufacture
The FY2026 national budget raised these limits from 3 years (private cars) and 7 years (light commercial), with effect from 1 January 2026. Confirm the current cap with the Ministry of Trade and Industry when you apply for the Import Licence — the licence conditions are what Customs will check.
Note that the tax reliefs carry their own, stricter age tests: a used hybrid must be no more than 3 years old and a used EV no more than 2 years old (for the customs-duty relief) to qualify.
A foreign-used vehicle also pays only 75% of the Motor Vehicle Tax that a new vehicle of the same engine size pays. The discount applies to the MVT only — customs duty and VAT are charged in full.
Electric and Hybrid Vehicles
Trinidad and Tobago relieves qualifying hybrids and electric vehicles of all three border taxes, through three separate legal instruments (one each for customs duty, MVT and VAT):
- Qualifying private hybrids — 0% duty, 0 MVT, 0% VAT. The vehicle must be imported for private use, have an engine of 1,599 cc or less, be a full hybrid (petrol or diesel engine and electric motor both drive the wheels), have an electric motor of no more than 105 kW, and, if used, be no more than 3 years old. Plug-in hybrids qualify on the same terms. There is no CIF value cap on the hybrid relief. The 105 kW limit applies to the electric motor alone, not to the combined system output.
- Hybrids that fail any test pay the most of any passenger car: 67.5% customs duty from the first cc, full MVT and 12.5% VAT. A 1,987 cc Toyota Corolla Cross Hybrid, for example, is over the 1,599 cc limit and pays about 102% of CIF in tax.
- Mild hybrids do not qualify. Under Classification Ruling General Order No. 24 of 2026 (22 July 2026), confirmed by the Minister of Finance on 30 July 2026, mild-hybrid systems whose electric motor cannot propel the car on its own — Suzuki SHVS and Smart Hybrid, Toyota NeoDrive, and 48-volt mild-hybrid systems — are taxed as ordinary petrol or diesel cars.
- Battery electric vehicles with CIF at or below TTD 400,000 (approximately USD 59,000): 0% duty, 0 MVT and 0% VAT, if imported for private use and, if used, no more than 2 years old.
- BEVs with CIF above TTD 400,000: since 1 January 2026 only 10% of the duty is remitted, so 18% customs duty is payable (90% of the 20% statutory rate), plus MVT charged per kilowatt of motor power and 12.5% VAT. The budget speech described this as a 10% duty, but the enacted order leaves 18% to pay. The cap is a cliff, not a taper: one dollar over TTD 400,000 moves a car from 0% to roughly 34% of CIF.
- CNG vehicles: commercial CNG vehicles of 1,599 cc or less (new, or used up to 8 years old) are relieved of customs duty and MVT. Relief for a privately imported CNG car is not confirmed — check with the Customs and Excise Division before relying on it.
Get exact duty rates for your specific electric or hybrid vehicle using CarImport.AI
Left-Hand-Drive Vehicles
Trinidad and Tobago drives on the left, and an LHD vehicle is not registrable for road use. A vehicle that has been converted from LHD to RHD is accepted. For buyers sourcing from LHD markets such as the USA, this means budgeting for a professional RHD conversion before the vehicle is shipped.
Fuel Types
All fuel types are eligible for importation — gasoline (petrol), diesel, CNG, electric, and hybrid. There is no blanket ban on any particular fuel type, though the tax treatment varies sharply: diesel cars pay more duty than petrol cars in the smaller engine bands, and full hybrids and EVs can qualify for complete relief.
Cars You Can Import to Trinidad & Tobago
Each card is a full landed-cost calculation: the car's price, shipping, every duty and tax, and handling, worked out on 9 November 2026 with the rules in force that day. All are right-hand drive to suit Trinidad & Tobago's roads. Tap a car to see its full breakdown, or open it to change the trim, colour or port.
More cars you can import to Trinidad & Tobago
New cars IPAS sources to order that meet Trinidad & Tobago's import rules. Prices are ex works, before shipping and duty. Cars marked C-RHD are built left-hand drive and converted to right-hand drive before shipping; the calculator adds the conversion. Open a car to work out its full landed cost.
 RHDBackorder2025
Ram 1500
Pickup · 6 VariantsPetrol · HybridFrom $70,800Ex Works, NZ LHD/C-RHDBackorder2026
Chevrolet Silverado 3500 HD
Pickup · 10 VariantsPetrol · DieselFrom $64,100Ex Works, USA LHD/C-RHDBackorder2025
Chevrolet Silverado 1500
Pickup · 29 VariantsPetrol · DieselFrom $57,800Ex Works, USA RHDBackorder2025
Lexus LX 700h
SUV · 5 VariantsHybridFrom $109,800Ex Works, Japan RHDBackorder2026
Volkswagen Tayron
SUV · 2 VariantsPetrolFrom $36,500Ex Works, India RHDBackorder2026
Renault Triber
Van & MPV · 18 VariantsPetrol · CNGFrom $6,700Ex Works, India RHDBackorder2026
Mercedes-Benz Maybach GLS
SUV · 1 VariantHybridFrom $219,900Ex Works, UK RHDBackorder2026
Suzuki Grand Vitara
SUV · 35 VariantsHybrid · CNGFrom $9,700Ex Works, India RHDBackorder2026
Kia Sorento
SUV · 32 VariantsDiesel · HybridFrom $25,200Ex Works, India RHDBackorder2026
Ford Mustang Fastback
Coupe · 2 VariantsPetrolFrom $89,100Ex Works, UK LHD/C-RHDBackorder2026
Toyota Tundra
Pickup · 10 VariantsPetrol · HybridFrom $49,500Ex Works, USA RHDBackorder2026
Toyota Hilux Champ
Pickup · 9 VariantsPetrol · DieselFrom $15,700Ex Works, Thailand RHDBackorder2026
Toyota Hilux Revo Standard Cab
Pickup · 6 VariantsDieselFrom $20,000Ex Works, Thailand LHD/C-RHDBackorder2025
GMC Hummer EV Pickup
Pickup · 2 VariantsElectricFrom $115,900Ex Works, USA RHDBackorder2026
Citroen eC3 X
Hatchback · 3 VariantsElectricFrom $14,400Ex Works, India RHDBackorder2026
Hyundai Exter
SUV · 19 VariantsPetrol · CNGFrom $6,700Ex Works, India
Seaports and Airports Supporting Vehicle Import
Trinidad and Tobago has two primary ports of entry for vehicle imports, one seaport and one airport:
| Port | Code | Type | City | Notes |
|---|---|---|---|---|
| Port of Spain | TTPOS | Seaport | Port of Spain | Primary vehicle import hub, operated by Port Authority of Trinidad and Tobago (PATT) |
| Piarco International Airport | POS | Airport | Piarco | Handles air-freighted vehicles and high-value shipments |
Port of Spain is the principal port for all containerised and RoRo vehicle imports. Operated by the Port Authority of Trinidad and Tobago (PATT), it handles the vast majority of vehicle cargo arriving in the country. The port has dedicated vehicle storage areas and customs inspection facilities.
Point Lisas, the country's secondary deepwater port approximately 40 kilometres south of Port of Spain, is primarily an industrial and petrochemical terminal. While it can handle overflow cargo, it is not the standard destination for vehicle imports and lacks dedicated vehicle processing infrastructure.
Piarco International Airport serves as the entry point for air-freighted vehicles. Air freight is typically used for high-value or time-sensitive shipments where the premium cost is justified by faster delivery — transit times of 2-5 days compared to 2-4 weeks by sea from most origins.
Restrictions on Vehicle Import for Individuals
Understanding who can import and under what conditions is critical before initiating a shipment to Trinidad and Tobago.
General Importers (Any Individual or Company)
- New RHD vehicles: Can be imported freely without an Import Licence
- Used RHD vehicles: Require an Import Licence from the Trade Licence Unit (TLU), Ministry of Trade and Industry, obtained via the TTBizLink online portal before the vehicle is shipped, and must be within the age limit
- LHD vehicles: Not registrable unless converted to RHD
Returning Nationals
Returning nationals — Trinidad and Tobago citizens returning after living overseas — previously received relief on the taxes payable on one personal vehicle. That has ended:
- The FY2026 Budget announced the removal of customs duty relief and the related VAT and MVT concessions for returning nationals, effective 1 January 2026
- The returning-national MVT relief in the Motor Vehicles and Road Traffic Act (Appendix A Part II) was formally revoked with effect from 1 July 2026 (L.N. 477/2025, re-enacted by L.N. 613/2026)
Returning nationals now pay the same customs duty, MVT and VAT as any other importer. One detail works against them: the 25% MVT discount for foreign-used vehicles is written for importers other than returning nationals.
Additional documents required for returning nationals include a travel pattern from the Immigration Department, proof of vehicle ownership, and proof of overseas address.
Diplomats
Diplomats accredited to Trinidad and Tobago import under their own diplomatic concessions, which are outside the scope of this guide.
Quantity Restrictions
There is no published per-year quantity limit for individual importers, but each used vehicle import requires a separate Import Licence from TLU, and licences are issued at the Ministry's discretion. Commercial importers (dealers) face separate licensing requirements.
Duty Structure Overview
Trinidad and Tobago applies a three-layer cascading tax structure on vehicle imports, with a relief layer that must be checked first. The total burden depends on fuel type, engine displacement, vehicle value and whether the car is new or foreign-used.
Step 1: Check the Relief Layer
Before calculating anything, check whether the vehicle is a qualifying private hybrid (up to 1,599 cc, electric motor up to 105 kW, used no more than 3 years old) or a private EV with CIF up to TTD 400,000. If it is, customs duty, MVT and VAT are all zero. If not, the full cascade below applies.
Layer 1: Customs Duty
Customs duty is charged as a percentage of the CIF (Cost, Insurance, Freight) value. The rate is set by the vehicle's 8-digit tariff line under the Customs (Common External Tariff) Order, 2024, in force since 1 January 2025 — and it depends on fuel type first and engine size second:
| Engine capacity | Petrol | Diesel |
|---|---|---|
| Up to 1,500 cc | 20% | 35% |
| 1,501-1,599 cc | 20% | 40% |
| 1,600-2,000 cc | 43.75% | 50% |
| 2,001-2,500 cc | 60% | 60% |
| 2,501-3,000 cc | 60% | 67.5% |
| Over 3,000 cc | 67.5% | 67.5% |
| Hybrid / plug-in hybrid (any cc, if not relieved) | 67.5% | 67.5% |
| Battery electric (if not relieved) | 20% | — |
| Goods vehicles, HS 8704 (pickups, vans, trucks) | 10% | 10% |
The 1,599 cc line is the biggest step in the petrol schedule: a 1,598 cc petrol car pays 20% duty and a 1,600 cc car pays 43.75%. Vehicles of CARICOM origin with a CARICOM Certificate of Origin pay 0% duty; no other origin — including Japan, the UK, India and the USA — receives a preferential rate.
Pickups: single-cab and extended-cab pickups with an open cargo bed are goods vehicles (10% duty). Pickup-based SUVs such as the Fortuner or Everest are passenger cars. Double-cab pickups are the grey area — confirm the tariff line with the Customs and Excise Division (or the TTBizLink tariff finder) before you buy, because the difference can exceed 50 percentage points of duty.
Layer 2: Motor Vehicle Tax (MVT)
The MVT is a unique feature of Trinidad and Tobago's import regime. Rather than being a percentage of vehicle value, it is charged as a TTD amount per cubic centimetre of engine displacement. This means a 5,000 cc V8 engine pays dramatically more MVT than a 1,500 cc four-cylinder, regardless of the vehicle's purchase price.
| Engine capacity (private cars) | MVT per cc |
|---|---|
| Up to 1,599 cc | TTD 5.00 |
| 1,600-1,799 cc | TTD 8.00 |
| 1,800-1,999 cc | TTD 15.00 |
| 2,000-2,499 cc | TTD 37.50 |
| 2,500-2,999 cc | TTD 45.00 |
| 3,000-3,499 cc | TTD 52.50 |
| 3,500 cc and above | TTD 75.00 |
| Goods vehicles (any cc) | TTD 2.50 |
The four bands from 2,000 cc upwards were raised by 50% in 2016, which is why large-displacement imports are so expensive. A foreign-used vehicle pays 75% of these amounts. Note that the MVT bands do not line up with the duty bands — look each one up separately. EVs above the TTD 400,000 cap pay MVT per kilowatt of motor power instead of per cc.
Layer 3: Value Added Tax (VAT)
VAT is charged at 12.5% on the aggregate of the CIF value, Customs Duty, and Motor Vehicle Tax. Because VAT is applied to the sum of all previous charges, it compounds the effective tax burden significantly.
Worked Examples
| Toyota Corolla 1.8 petrol (1,798 cc), new | Toyota Harrier 2.4 petrol (2,362 cc), new | Toyota Urban Cruiser Hyryder full hybrid (1,490 cc, 59 kW motor), new | |
|---|---|---|---|
| CIF | TTD 100,000 | TTD 150,000 | TTD 200,659 |
| Customs Duty | 43.75% = TTD 43,750 | 60% = TTD 90,000 | 0 (relieved) |
| MVT | 1,798 × TTD 8.00 = TTD 14,384 | 2,362 × TTD 37.50 = TTD 88,575 | 0 (relieved) |
| VAT 12.5% | TTD 19,766.75 | TTD 41,071.88 | 0 (relieved) |
| Total taxes | TTD 77,900.75 | TTD 219,646.88 | TTD 0 |
| Effective rate | 77.90% of CIF | 146.43% of CIF | 0% |
The mild-hybrid NeoDrive version of the same Hyryder (1,462 cc) gets no relief: at a CIF of TTD 150,000 it pays 20% duty, TTD 7,310 MVT and VAT — about 40% of CIF in tax.
Effective Total Tax Burden
The combined effect of these three layers means:
- Qualifying full hybrids and EVs up to TTD 400,000 CIF: 0%
- Small petrol cars (up to 1,599 cc): Total taxes typically add about 40-45% to the CIF value
- Mid-range petrol cars (1,600-2,000 cc): Total taxes typically add about 75-95% to the CIF value
- Large-displacement vehicles (above 2,000 cc): Total taxes typically add 120-210% to the CIF value, driven heavily by the MVT
- Hybrids that miss the relief tests: often around 100% of CIF, because the 67.5% hybrid duty has no low-cc band
The MVT component is especially impactful on large trucks and SUVs with engines above 3,500 cc, where the per-cc charge can easily exceed the vehicle's customs duty.
Get exact duty rates for your specific vehicle using CarImport.AI. The calculator applies the relief tests, the propulsion-specific duty table, the per-cc MVT and VAT to give you a total landed cost.
Calculate your exact import duty to Trinidad & Tobago
Get a vehicle-specific duty and full landed-cost breakdown — HS classification, every tax, levy and FTA, plus shipping — calculated for your exact make, model and specs.
- Vehicle-specific HS code
- All duties, taxes & FTAs
- Shipping + est. landed cost
Worked Example: Importing a 2026 Toyota Urban Cruiser Taisor to Trinidad & Tobago
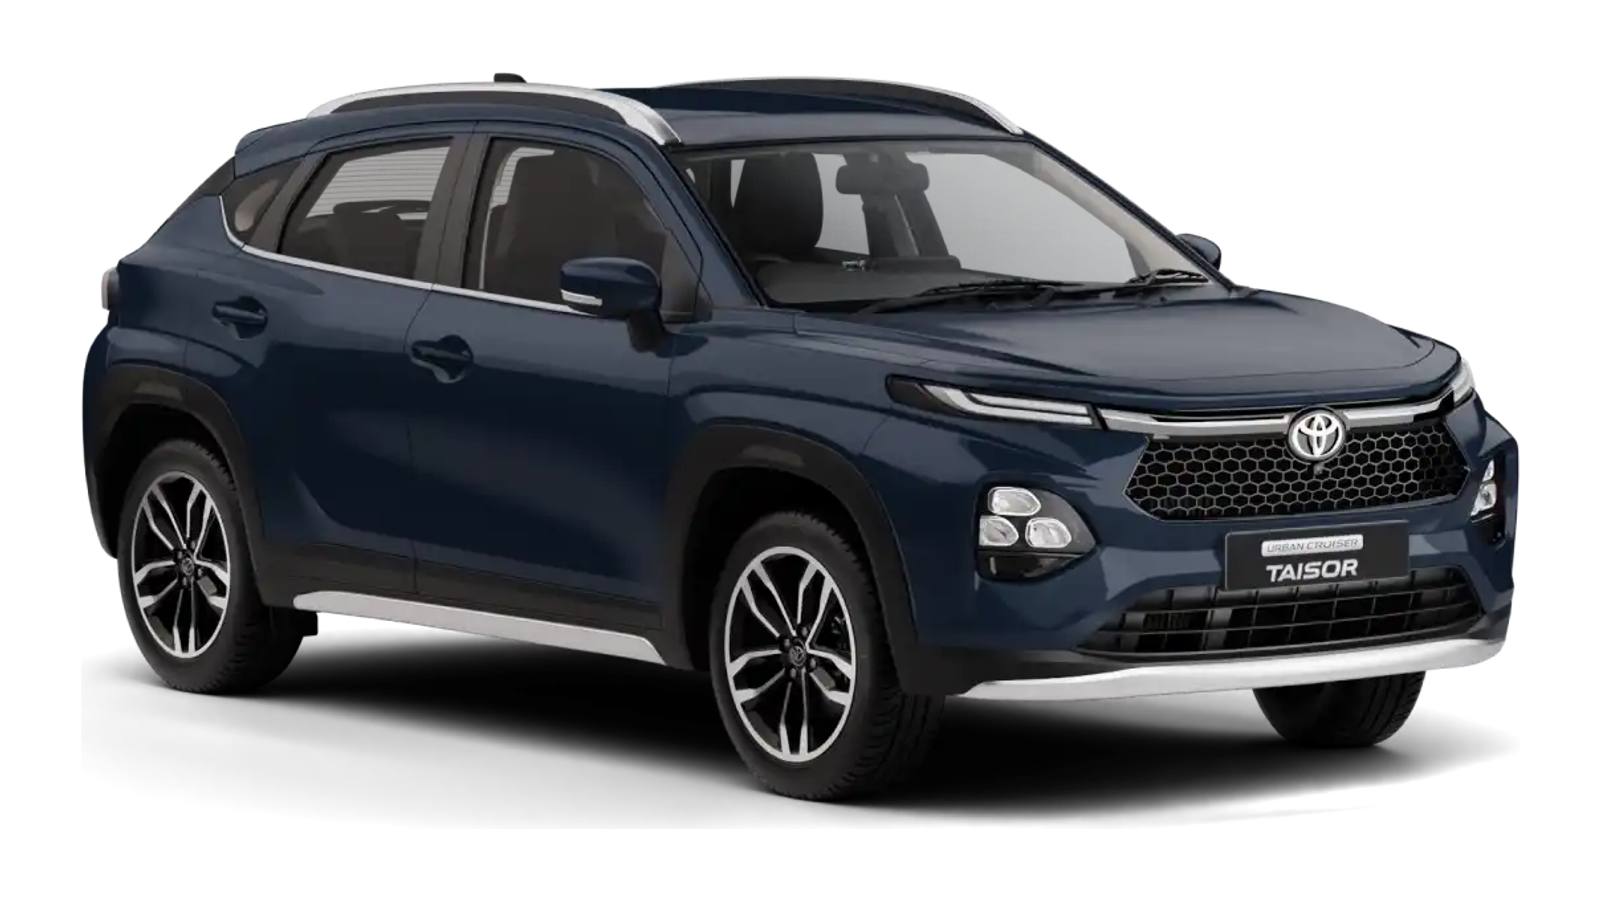
Here is the full landed cost of one car, a 2026 Toyota Urban Cruiser Taisor shipped from India to Trinidad & Tobago, worked out on 9 November 2026 with the customs rules in force that day. It lands at 197,189 TTD (about US$29,192), and duties and taxes come to 40.3% of its CIF value.
| Item | Share of CIF | Amount |
|---|---|---|
| Vehicle priceIPAS price for a car sourced in India | 55,390 TTDUS$8,200 | |
| Shipping and insuranceIndia to Trinidad & Tobago | 72,872 TTDUS$10,788 | |
| CIF valueCost, insurance and freight: the customs value | 128,262 TTDUS$18,988 | |
| Customs duties and taxes | ||
| Basic customs duty (20%)20% of CIF | 25,655 TTDUS$3,798 | |
| Additional duty4.7% of CIF | 5,985 TTDUS$886 | |
| GST/VAT (12.5%)12.5% of CIF plus the duties above15.6% of CIF | 19,988 TTDUS$2,959 | |
| Total duties and taxes40.3% of CIF | 51,628 TTDUS$7,643 | |
| Service and handling | ||
| Premium Import ServiceOptional end-to-end import management by IPAS | 5,309 TTDUS$786 | |
| Destination handlingPort terminal and customs clearance handling | 11,990 TTDUS$1,775 | |
| Total landed cost | 197,189 TTDUS$29,192 | |
Documents Required for Import
Importing a vehicle to Trinidad and Tobago requires a comprehensive set of documents. Missing or incomplete paperwork is the most common cause of clearance delays at Port of Spain.
Core Customs Documents
- Customs Declaration Form (C82 Form) — Four copies required, completed with accurate vehicle details and declared CIF value
- CARICOM Area Invoice — Required for imports from CARICOM member states; issued by the supplier
- Supplier's Invoice / Commercial Invoice — Detailing the vehicle description, price, and terms of sale
- Bill of Lading — Original or express release; must match the details on all other documents
- Certificate of Origin — Confirming the country of manufacture
- Tax Identification Number (TIN) — Importer must have a valid TIN or Importer Registration Number
Vehicle-Specific Documents
- Deregistration Certificate — From the country of export, confirming the vehicle has been deregistered for international transfer
- Vehicle Registration History — Showing previous ownership and registration details
- Manufacturer specifications (hybrids and EVs) — If you are claiming hybrid or EV relief, have the engine capacity and electric motor rating (kW) documented, as both are tested
Licence and Identity Documents
- Import Licence — Required for all used vehicle imports; must be obtained from the Trade Licence Unit (TLU) via TTBizLink before shipment. Not required for new vehicles.
- Valid Passport or National ID — Proof of importer identity
- Two passport-size photographs — Required as part of the Import Licence application
Additional Documents for Returning Nationals
- Travel Pattern — Obtained from the Immigration Department, showing your period of overseas residence
- Proof of Vehicle Ownership — Demonstrating your ownership of the vehicle
- Proof of Overseas Address — Utility bills, lease agreements, or similar documentation
Tips for Smooth Document Processing
- Ensure the CIF value on the Commercial Invoice matches the declared value on the C82 Form — discrepancies trigger valuation audits
- Obtain the Import Licence via TTBizLink before shipping the vehicle. Applying after shipment risks the vehicle being held at port until the licence is granted
- Keep all originals plus at least two copies of every document. Customs may retain originals during processing
- If using a Customs Broker (mandatory for commercial imports), provide documents at least 5 business days before vessel arrival
Customs Clearance Timeline
The customs clearance process in Trinidad and Tobago follows a structured sequence. Timelines are estimates based on typical processing and assume complete documentation.
| Stage | Duration | Details |
|---|---|---|
| Pre-arrival: Obtain Import Licence | 5-15 business days | Apply via TTBizLink before vehicle is shipped; processing times vary |
| Vessel transit (from USA/Japan) | 10-25 days | Sea freight transit time depends on origin port and routing |
| Cargo manifest lodged | Day of arrival | Shipping line submits manifest to Customs and Excise Division |
| Document submission | 1-2 business days | Submit C82 Form and supporting documents to Customs |
| Physical inspection and valuation | 1-3 business days | Customs officer inspects vehicle, verifies VIN, checks condition, confirms CIF value |
| Duty assessment and invoice | 1-2 business days | Customs calculates duty, MVT, and VAT; issues payment invoice |
| Duty payment | Same day | Payment made to Customs and Excise Division |
| Vehicle release from port | 1-2 business days | Vehicle cleared for collection after payment confirmation |
| VMCOTT inspection | 1-2 business days | Tyre and roadworthiness inspection (post-release) |
| Registration at Licensing Office | 1-2 business days | Final registration, plates, and insurance |
Total estimated timeline: 3-7 business days for customs clearance after vessel arrival (assuming all documents are in order and the Import Licence was obtained in advance). Add 2-4 business days for post-clearance VMCOTT inspection and registration.
Common causes of delay:
- Import Licence not obtained before shipping (can add weeks)
- CIF value discrepancy between invoice and customs valuation (triggers audit)
- Incomplete C82 Form or missing photographs
- Vehicle age exceeding the applicable limit (vehicle may be refused entry)
- A hybrid or EV relief claim without the specifications to support it
Using a licensed Customs Broker is mandatory for commercial imports and strongly recommended for private importers unfamiliar with the process. Brokers charge a fee (typically TTD 2,000-5,000) but significantly reduce the risk of processing errors and delays.
Homologation and Vehicle Approval
Trinidad and Tobago does not maintain a formal type-approval or homologation system comparable to those in Australia, the UK, or Japan. The country's vehicle compliance requirements are less technical but still must be met before a vehicle can be registered for road use.
VMCOTT Inspection
The Vehicle Maintenance Corporation of Trinidad and Tobago (VMCOTT) conducts a mandatory inspection of all imported vehicles before they can be registered. This inspection covers:
- Tyre condition and specification — Tyres must be in serviceable condition and appropriate for the vehicle
- General roadworthiness — Brakes, lights, mirrors, steering, and structural integrity are checked
- VIN verification — The Vehicle Identification Number must match the customs documentation
The VMCOTT inspection is not an emissions test or a comprehensive engineering assessment. It is a safety and condition check designed to ensure the vehicle is fit for road use in its current state.
Headlight Configuration
Vehicles must have headlights configured for left-hand traffic (the standard in Trinidad and Tobago). Right-hand-drive vehicles from Japan and the UK typically have correctly configured headlights by default. Vehicles from continental Europe or other RHD markets with different beam patterns may need headlight adjustment.
Emissions Standards
Trinidad and Tobago does not currently impose separate emissions certification requirements at the point of import. There is no equivalent of the Euro 6, WLTP, or EPA emissions standards that must be met before a vehicle can be cleared. This simplifies the import process compared to markets like Australia or the UK, where emissions compliance is a significant regulatory hurdle.
Modifications and Aftermarket Equipment
The VMCOTT inspection applies to the vehicle as presented. Significant aftermarket modifications — particularly to the suspension, exhaust, or body structure — may raise questions during the inspection. Factory-standard vehicles generally pass without issue.
Registration Procedures and Costs
Once a vehicle has cleared customs and passed the VMCOTT inspection, the registration process is straightforward.
Step-by-Step Registration Process
- VMCOTT Inspection — Drive the vehicle (without plates) to a VMCOTT centre. Present customs clearance documents and proof of ownership. The inspection typically takes 1-2 hours, and the vehicle receives a clearance certificate upon passing.
- Licensing Office Visit — Proceed to the Licensing Authority of Trinidad and Tobago with the following documents:
- VMCOTT clearance certificate
- Customs duty payment receipts
- Proof of ownership (Bill of Sale, Invoice)
- Valid identification (passport or national ID)
- Deregistration certificate from origin country
- Certified Extract Issued — The Licensing Authority issues a Certified Extract, which contains the vehicle's assigned licence plate number and registration details.
- Insurance — Purchase a Cover Note (temporary insurance) from an insurer at the Licensing Office. This provides immediate coverage while full insurance is arranged. Subsequently obtain full motor vehicle insurance from a licensed insurer.
- Collect Number Plates — Plates are issued upon completion of registration and insurance verification.
Registration Costs
| Item | Estimated Cost |
|---|---|
| VMCOTT inspection fee | TTD 200-500 |
| Licensing Office registration | TTD 500-1,000 |
| Cover Note (temporary insurance) | TTD 300-600 |
| Full motor vehicle insurance (annual) | TTD 3,000-15,000+ (varies by vehicle value and type) |
| Number plates | Included in registration fee |
| Environmental Tyre Tax | Raised from TTD 20 to TTD 40 from 1 January 2026 |
Note on tyre tax: The FY2026 Budget doubled the Environmental Tyre Tax from TTD 20 to TTD 40, effective 1 January 2026. It is a small charge next to customs duty, MVT and VAT.
Frequently Asked Questions
Q: Can I import a left-hand-drive vehicle to Trinidad and Tobago? A: Not for road use as it is. Trinidad and Tobago drives on the left and an LHD vehicle is not registrable. A vehicle professionally converted to right-hand drive is accepted, so an LHD car from the USA or Europe needs an RHD conversion before it ships.
Q: What is the used car age limit for imports in 2026? A: From 1 January 2026, private cars (sedans, SUVs, station wagons) with gasoline, diesel or CNG engines must be 6 years old or less from the date of manufacture, and light commercial vehicles (pickups, panel vans) 10 years or less. The previous limits were 3 and 7 years. Confirm the cap on your Import Licence with the Ministry of Trade and Industry.
Q: Do I need an Import Licence for a new vehicle? A: No. Import Licences are only required for used vehicle imports. New vehicles can be imported by any individual or company without a licence, subject to the standard customs duty, MVT, and VAT (or the hybrid and EV reliefs).
Q: Do hybrid cars pay import duty in Trinidad and Tobago? A: A qualifying private full hybrid pays nothing: 0% duty, 0 MVT and 0% VAT. It must have an engine of 1,599 cc or less and an electric motor of 105 kW or less, and if used be no more than 3 years old. Mild hybrids (SHVS, NeoDrive, 48-volt systems) do not qualify, and a hybrid that fails any test pays 67.5% duty plus MVT and VAT.
Q: How much does Motor Vehicle Tax (MVT) add to the cost of a large truck or SUV? A: The MVT can be substantial for large-displacement vehicles. A 5,700 cc V8 passenger vehicle is in the top band at TTD 75.00 per cc — TTD 427,500 of MVT if new, or TTD 320,625 if foreign-used. For large trucks and SUVs, the MVT alone can exceed the customs duty amount. Use CarImport.AI to calculate the exact MVT for your specific vehicle.
Q: Are electric vehicles cheaper to import than petrol or diesel vehicles? A: Usually, yes. A private EV with a CIF value at or below TTD 400,000 (approximately USD 59,000) pays 0% duty, 0 MVT and 0% VAT (used EVs must be no more than 2 years old). Above that cap, since 1 January 2026, the EV pays 18% customs duty, MVT per kilowatt and 12.5% VAT — roughly a third of CIF in total. Mid-range EVs remain far cheaper to import than equivalent petrol or diesel vehicles.
Q: What happens if my vehicle exceeds the age limit? A: The vehicle will be denied entry at customs. You may be required to re-export the vehicle at your own expense, or it could be seized and auctioned. Always verify the vehicle's age against the applicable limit before shipping.
Q: Can I ship my own vehicle from the USA to Trinidad? A: Only if it is right-hand drive. US vehicles are left-hand drive, so a US car must be converted to RHD before it can be registered, and a used vehicle also needs an Import Licence and must be within the age limit. Use IPAS EXPRESS Pro Car Shipping to get an instant shipping quote for your specific route.
Q: How long does the entire import process take from purchase to registration? A: From the time of purchase to having a registered, plated vehicle on the road, expect 4-8 weeks total. This includes 1-3 weeks for shipping (depending on origin), 1-2 weeks for customs clearance and duty payment, and 3-5 business days for VMCOTT inspection and registration. The longest potential delay is the Import Licence application, which should be submitted well before shipping.
Q: Are returning nationals still exempt from duties in 2026? A: No. The FY2026 Budget removed the customs duty, VAT and MVT concessions for returning nationals from 1 January 2026, and the MVT relief was formally revoked with effect from 1 July 2026. Returning nationals now pay the same rates as any other importer.
Ready to Import?
Importing a vehicle to Trinidad and Tobago involves navigating a three-layer tax structure, a relief layer for hybrids and EVs, age restrictions, and an Import Licence requirement for used vehicles. Getting the numbers right before you commit is essential — the same model can pay 0% as a full hybrid and 40% as a mild hybrid, and the Motor Vehicle Tax creates dramatically different costs depending on engine displacement.
Two tools to get started:
CarImport.AI — Calculate the full landed cost of any vehicle to Trinidad and Tobago, including customs duty, Motor Vehicle Tax, VAT, and shipping. The calculator applies the hybrid and EV relief tests, the fuel-specific duty table and the per-cc MVT to give you a full breakdown.
IPAS EXPRESS Pro Car Shipping — Already have a vehicle? Get instant shipping quotes to Port of Spain or Piarco International Airport. Compare sea freight (container and RoRo) with air freight, and see a full cost breakdown including terminal handling, insurance, and customs processing fees.
Ready to Import Your Vehicle?
Two tools, two use cases. Pick the one that fits your needs.
Source a vehicle through IPAS and calculate the full landed cost — customs duties, shipping, and compliance — to destinations across the world.
Calculate Landed CostIPAS Express
Already have a vehicle? Get instant shipping quotes — sea freight, air freight, or RoRo — for one car or multiple vehicles worldwide.
Get Shipping Quote